
By Phil Irwin, LUTCF, CLCS · Gold Insurance Solutions · Wildfire Country Home Insurance Experts
Do you need umbrella insurance in California? It’s a fair question for a lot of households: a teen who just got a license, a pool in the backyard, a dog that greets every guest, an ADU rented to a tenant, or a home listed as a short-term rental. Whether you live in Folsom, El Dorado Hills or Granite Bay, in the Sierra foothills and Gold Country, or in the North Bay wine country, here’s what a personal umbrella policy is, what it usually covers, what it doesn’t, and how to decide if it fits your situation.
What is umbrella insurance?
A personal umbrella policy is extra liability coverage that sits on top of your home and auto policies. Maryland’s insurance regulator puts it simply: an umbrella “provides extra liability insurance protection above the policy limits” of your homeowners and auto policies.
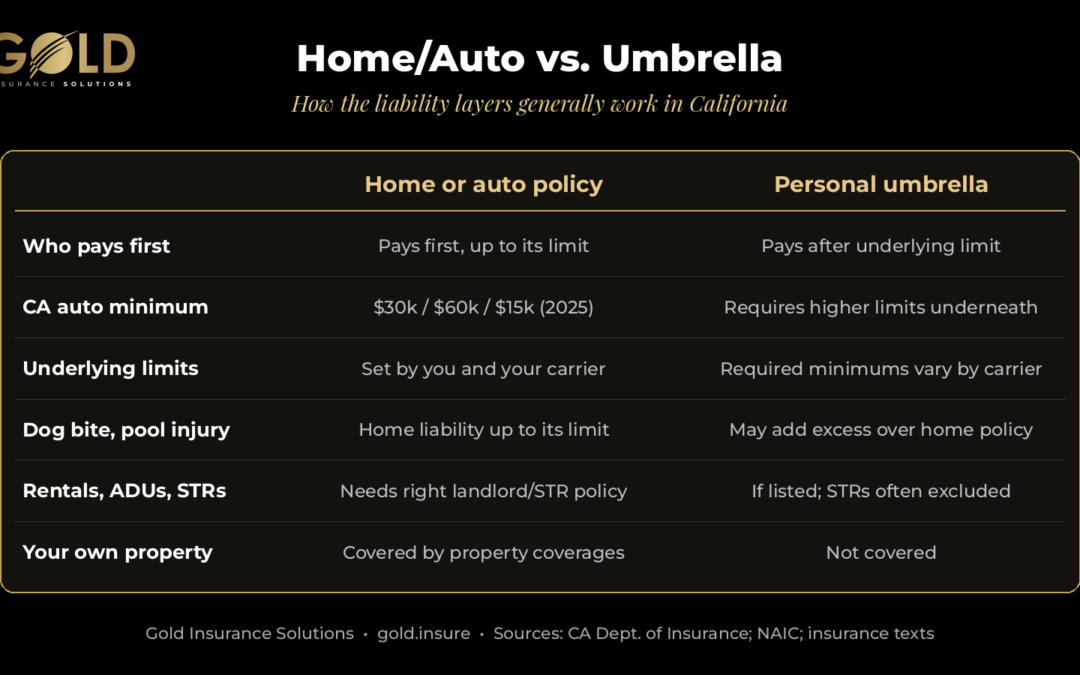
Here’s how the layers work:
- Your home or auto policy pays first, up to its liability limit.
- The umbrella pays next, up to its own limit, once the underlying limit is used up.
- Some umbrellas also fill certain gaps. According to the NAIC, an umbrella can cover liability claims your primary policy doesn’t, as well as costs “that exceed the amount your primary insurance policy will pay.” That can include bodily injury, property damage and personal injury, plus defense costs.
How much umbrella coverage you buy is up to you and the carrier. The Maryland advisory uses a $1,000,000 umbrella as its example.
Why California’s minimum auto limits matter
On January 1, 2025, California raised its minimum auto liability limits under Senate Bill 1107 (Chapter 717, Statutes of 2022). According to the California Department of Insurance, standard auto policies now carry these minimums as they renew:
- $30,000 for bodily injury or death per person (up from $15,000)
- $60,000 for bodily injury or death per accident (up from $30,000)
- $15,000 for property damage per accident (up from $5,000)
That’s an improvement. But a minimum is just that: the least the law allows. A serious crash involving several cars or injured people can exceed even much higher limits. When damages go past your policy, the remaining amount can become your responsibility.
That’s also why umbrella carriers don’t accept minimum limits underneath. They generally require you to carry higher auto and home liability limits first, which we cover below. For more on the auto side, see our guide to California auto insurance rates and the home insurance crisis.
What are the underlying limit requirements?
Every umbrella carrier sets its own required underlying limits, and they vary. One insurance textbook’s example uses auto limits of $100,000/$300,000/$50,000 and $300,000 of personal liability on the homeowners policy. Some carriers require more, and you may need to list rental properties, watercraft or other vehicles with their own minimums.
This matters for two reasons:
- Your auto and home limits may need to go up before an umbrella can be written. That can change your auto and home premiums too.
- A gap can cost you. According to an Insurance Journal review of a standard umbrella form, if you don’t keep the required underlying limits, the umbrella may not pay until the loss reaches the level it expected underneath.
Common situations where umbrella coverage helps
Teen drivers and auto accidents
Adding a newly licensed driver is one of the most common reasons families ask about an umbrella. Insurance Journal’s example is exactly this: “a child starts driving,” followed by a serious multi-vehicle accident with injuries that could exceed the auto policy’s limits.
Dog bites
California is a strict liability state for dog bites. Under Civil Code § 3342, a dog’s owner is liable for damages when someone is bitten in a public place or lawfully on private property, “regardless of the former viciousness of the dog or the owner’s knowledge of such viciousness.” Your homeowners liability is the first layer; an umbrella can add more above it, subject to the carrier’s rules on dogs.
Pools, trampolines and entertaining
A backyard pool in the Sacramento summer heat brings friends, neighbors and kids. More guests means more chances for an injury on your property. Carriers have their own underwriting rules for pools and similar features, so ask before you assume.
Rental units and ADUs
If you rent out a house, a condo or an ADU, a personal umbrella may extend over the rental, but not automatically. Many umbrellas require each rental to be listed and to carry its own underlying landlord liability at a required limit, and some exclude rentals owned by an LLC as business activity. See our guide to ADU and rental property insurance in California for how the underlying coverage works.
Short-term rentals
Hosting on a short-term rental platform in Napa, Sonoma, Lake Tahoe or the foothills? Be careful. The Texas Department of Insurance warns that homeowners insurance “probably won’t cover the costs if someone else gets hurt or causes damage on your property” during a home-share. Because most umbrellas follow the underlying policy, an umbrella generally won’t fill that gap if your base policy excludes rental activity. You may need a policy designed for short-term rentals first.
What umbrella insurance usually doesn’t cover
An umbrella is liability coverage. It protects you when you’re responsible for harm to others, not for damage to your own things. Common exclusions, depending on the policy, include:
- Your own property. The NAIC notes it doesn’t cover damage to your home or vehicle, and the textbook overview lists property you own or control.
- Business pursuits and professional services, unless underlying coverage applies.
- Intentional acts meant to cause injury or damage.
- Certain aircraft and watercraft excluded by the homeowners policy, unless listed with required underlying coverage.
- Punitive damages, in some cases. The NAIC gives drunk driving as an example.
Exclusions vary by carrier, so read the actual policy or ask your broker to walk you through it.
Do you need umbrella insurance? Questions to ask
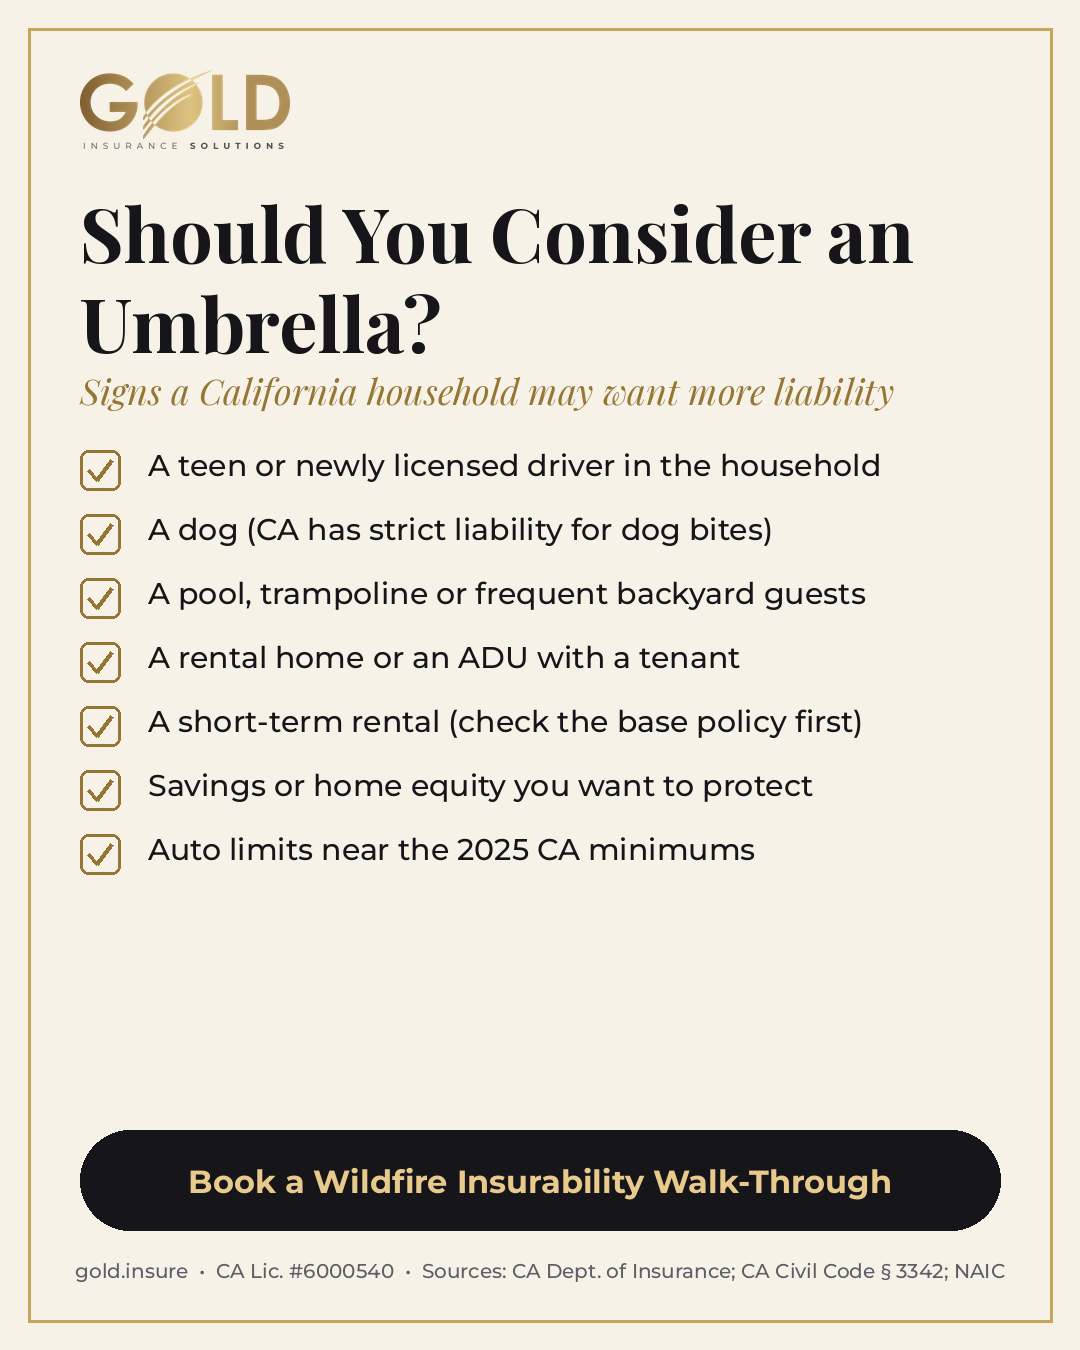
There’s no single right answer. Consider an umbrella if you can say yes to any of these:
- Do you have a teen or new driver in the household?
- Do you have a dog, a pool or a trampoline?
- Do you entertain often or host large gatherings?
- Do you own a rental, an ADU with a tenant, or a short-term rental?
- Do you have savings, home equity or future earnings you want to protect?
- Could an auto accident in your household realistically exceed your current limits?
Then review your current auto and home liability limits, check what an umbrella carrier requires underneath, and compare the total cost, including any increase to your underlying limits.
How we help
At Gold Insurance Solutions, we look at your home, auto and umbrella together, so the layers fit and there’s no gap between them. We check your current limits against what umbrella carriers require, and we review rentals, ADUs and short-term rental use so you know what’s covered and what needs its own policy.
For homeowners in wildfire country, our free Wildfire Insurability Walk-Through is an in-person, exterior review of your property through each carrier’s underwriting lens. We identify mitigation priorities and help you plan for them, validate the home hardening you’ve already done, and help you determine if your home qualifies for Mercury, our top carrier in the California home insurance market. If it doesn’t, we shop our other admitted carriers. A strong home policy is the foundation an umbrella sits on.
Book a free review: calendly.com/phil_irwin_availability/30min · Get a free quote: gold.insure/quote · Realtors: send quote requests to quote@gold.insure
Frequently asked questions
What does umbrella insurance cover in California?
A personal umbrella adds liability coverage above your home and auto policies, and may cover certain claims those policies don’t, such as personal injury. It pays for harm you cause to others, not damage to your own property.
What are California’s minimum auto liability limits?
Since January 1, 2025, standard auto policies must carry at least $30,000 per person and $60,000 per accident for bodily injury or death, and $15,000 for property damage, under SB 1107.
Can I buy an umbrella with minimum auto limits?
Generally, no. Umbrella carriers set required underlying limits for auto and home liability that are typically higher than state minimums, and the requirements vary by carrier.
Does an umbrella cover my rental property or ADU?
It may, if the carrier allows it and the rental is listed with the required underlying landlord liability. Some umbrellas exclude rentals held in an LLC.
Does a personal umbrella cover short-term rentals?
Often not. Most umbrellas follow the underlying policy, so if your home policy excludes short-term rental activity, the umbrella generally won’t respond.
Is California a strict liability state for dog bites?
Yes. Under Civil Code § 3342, a dog owner is liable for bite damages to someone in a public place or lawfully on private property, regardless of the dog’s history.
Phil Irwin, LUTCF, CLCS, is President of Gold Insurance Solutions in El Dorado Hills, with more than 30 years in insurance. CA License #0G50873 · Agency License #6000540. This article is general information, not a guarantee of coverage, eligibility or discounts.
Sources: CDI: New Year Means New Changes for Insurance · CDI: California’s Low Cost Auto Insurance (July 2024) · CDI Bulletin 2023-1: SB 1107 · NAIC: What’s an Umbrella Policy? · Maryland Insurance Administration: Umbrella Insurance · Insurance Journal: What Is Umbrella Coverage? · Risk Management for Enterprises and Individuals: Personal Umbrella Liability Policies · California Civil Code § 3342 · Texas Department of Insurance: Home Sharing · Coverage Cat: Personal Umbrellas for Landlords · Proper Insurance: Umbrella Policies and STRs