
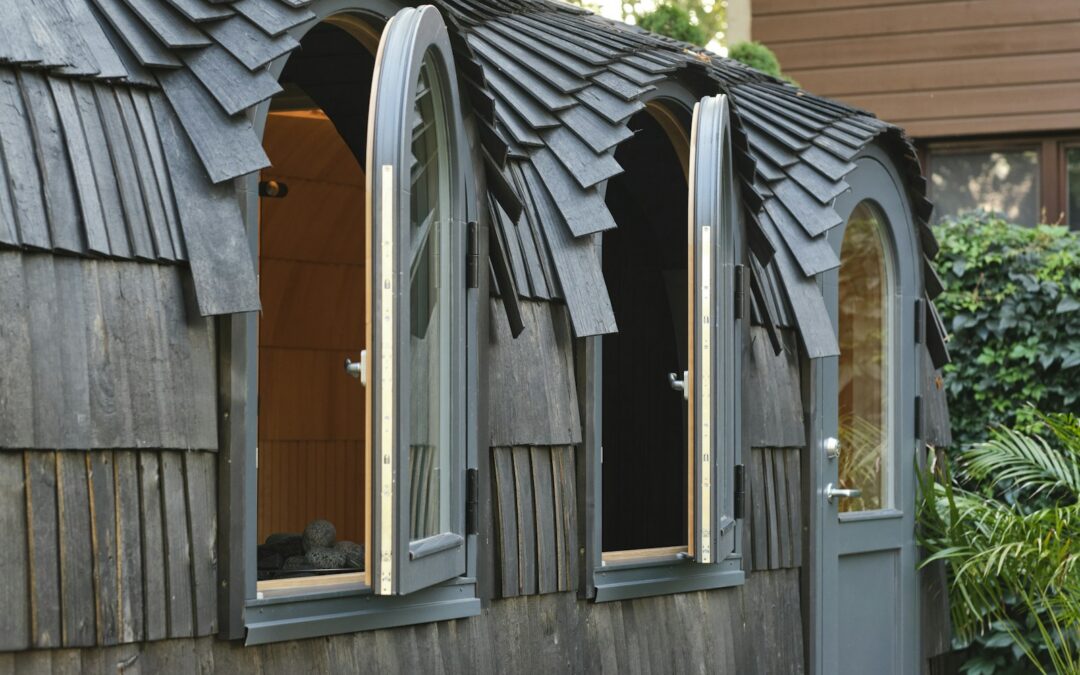
California’s ADU laws have made it much easier to build accessory dwelling units, and backyard cottages, garage conversions and junior ADUs are popping up across the Sierra foothills. But many homeowners never update their insurance, and a standard policy may not fully cover an ADU, especially one that’s rented out.
Here’s how to insure an ADU or a rental property in California the right way.
Attached or detached? It matters
- Attached ADUs and junior ADUs (JADUs) are generally part of your home and covered under your dwelling limit. Make sure that limit was raised to include the added square footage and finishes.
- Detached ADUs usually fall under Other Structures, which is often just 10% of your dwelling limit. On a $600,000 home, that’s $60,000, likely far less than it costs to rebuild a new ADU. You can usually raise it, or insure the ADU separately.
Renting it out changes everything
Long-term tenants
- Disclose the rental. Many homeowners policies limit or exclude coverage for parts of the home rented to others unless you tell the insurer and add the right coverage.
- Fair Rental Value: replaces lost rent if a covered loss makes the ADU unlivable. See Loss of Use Explained.
- Liability: you’re now a landlord. Make sure your liability limit is strong, and consider an umbrella policy.
- Your tenant’s belongings aren’t covered by your policy. Require renters insurance in your lease.
Short-term rentals
Renting to guests for short stays usually needs coverage built for short-term rentals, and many California towns require permits and fire safety measures. See our Truckee and Lake Tahoe guide for an example.
Whole-home rentals
If you rent out an entire property you don’t live in, a homeowners policy usually isn’t the right fit. You’ll need a landlord or dwelling fire policy, with Fair Rental Value and premises liability. In wildfire areas, some landlord properties end up on the FAIR Plan with a companion policy, so the same admitted, non-admitted and FAIR Plan considerations apply.
Building an ADU?
- Before construction: ask about builder’s risk or course of construction coverage, and make sure your contractor carries liability and workers’ compensation.
- When it’s done: update your dwelling or other structures limit, and tell us how it will be used.
- Build with wildfire in mind: Class A roofing, ember-resistant vents and noncombustible siding help with insurability too.
Your ADU and rental checklist
- Confirm whether your ADU is attached or detached.
- Set your dwelling or other structures limit to the ADU’s full rebuild cost.
- Tell your insurer if it’s rented, and how.
- Add Fair Rental Value and strong liability coverage.
- Require tenants to carry renters insurance.
- Use a landlord policy for whole-home rentals.
- Review coverage every year.
Let’s make sure your ADU is covered
Tell us about your ADU or rental and we’ll make sure it’s insured correctly. Book a 30-minute review with me or request a free quote. Current clients with questions about an existing policy or renewal can reach our service team at team@gold.insure.
Specialists in California’s wildland-urban interface, where homes meet forest, brush and grassland.
Phil Irwin, President, Gold Insurance Solutions. CA License #6000540. General information as of October 2026, not legal advice. Coverage and pricing vary by carrier and home.