
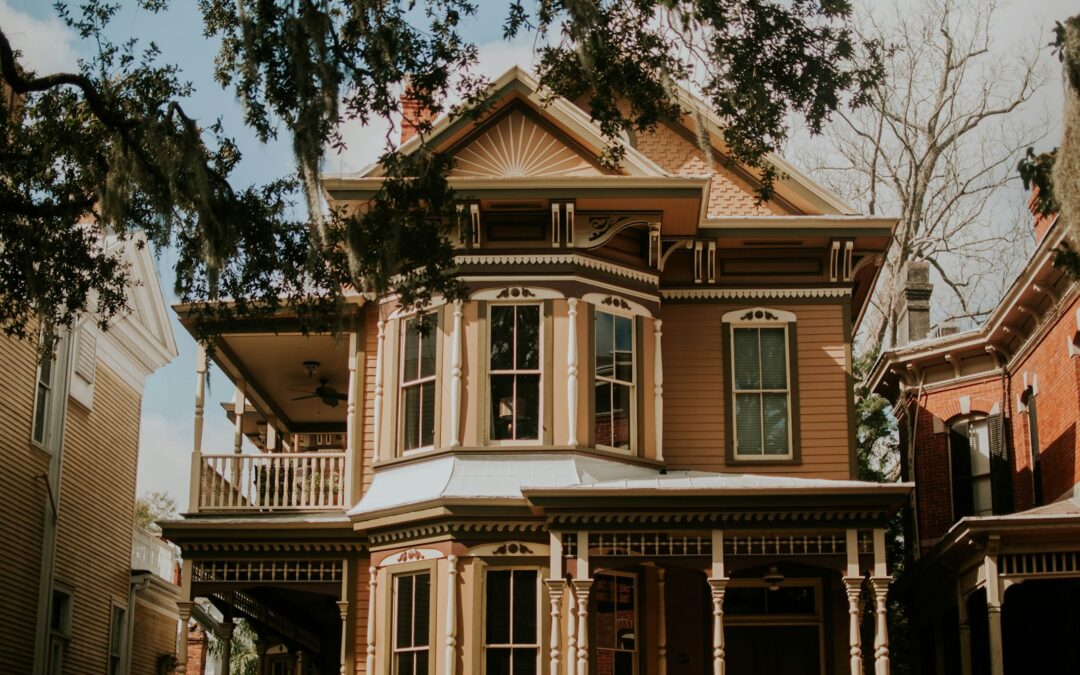
Gold Country is full of character: Victorian homes in Nevada City, historic cottages in Grass Valley, older ranch homes around Auburn and cabins in the Sierra. Older homes are wonderful to live in, but they can be harder to insure, especially if their original systems haven’t been updated.
Here’s what insurers look for in an older California home, and how to make yours easier to insure.
Why insurers look harder at older homes
- Fire risk from aging wiring and electrical panels.
- Water damage risk from old pipes, which is one of the most common claims.
- Higher rebuild costs to meet today’s building codes after a loss.
- Unknown updates. Without records, insurers may assume original systems.
Red flags insurers ask about
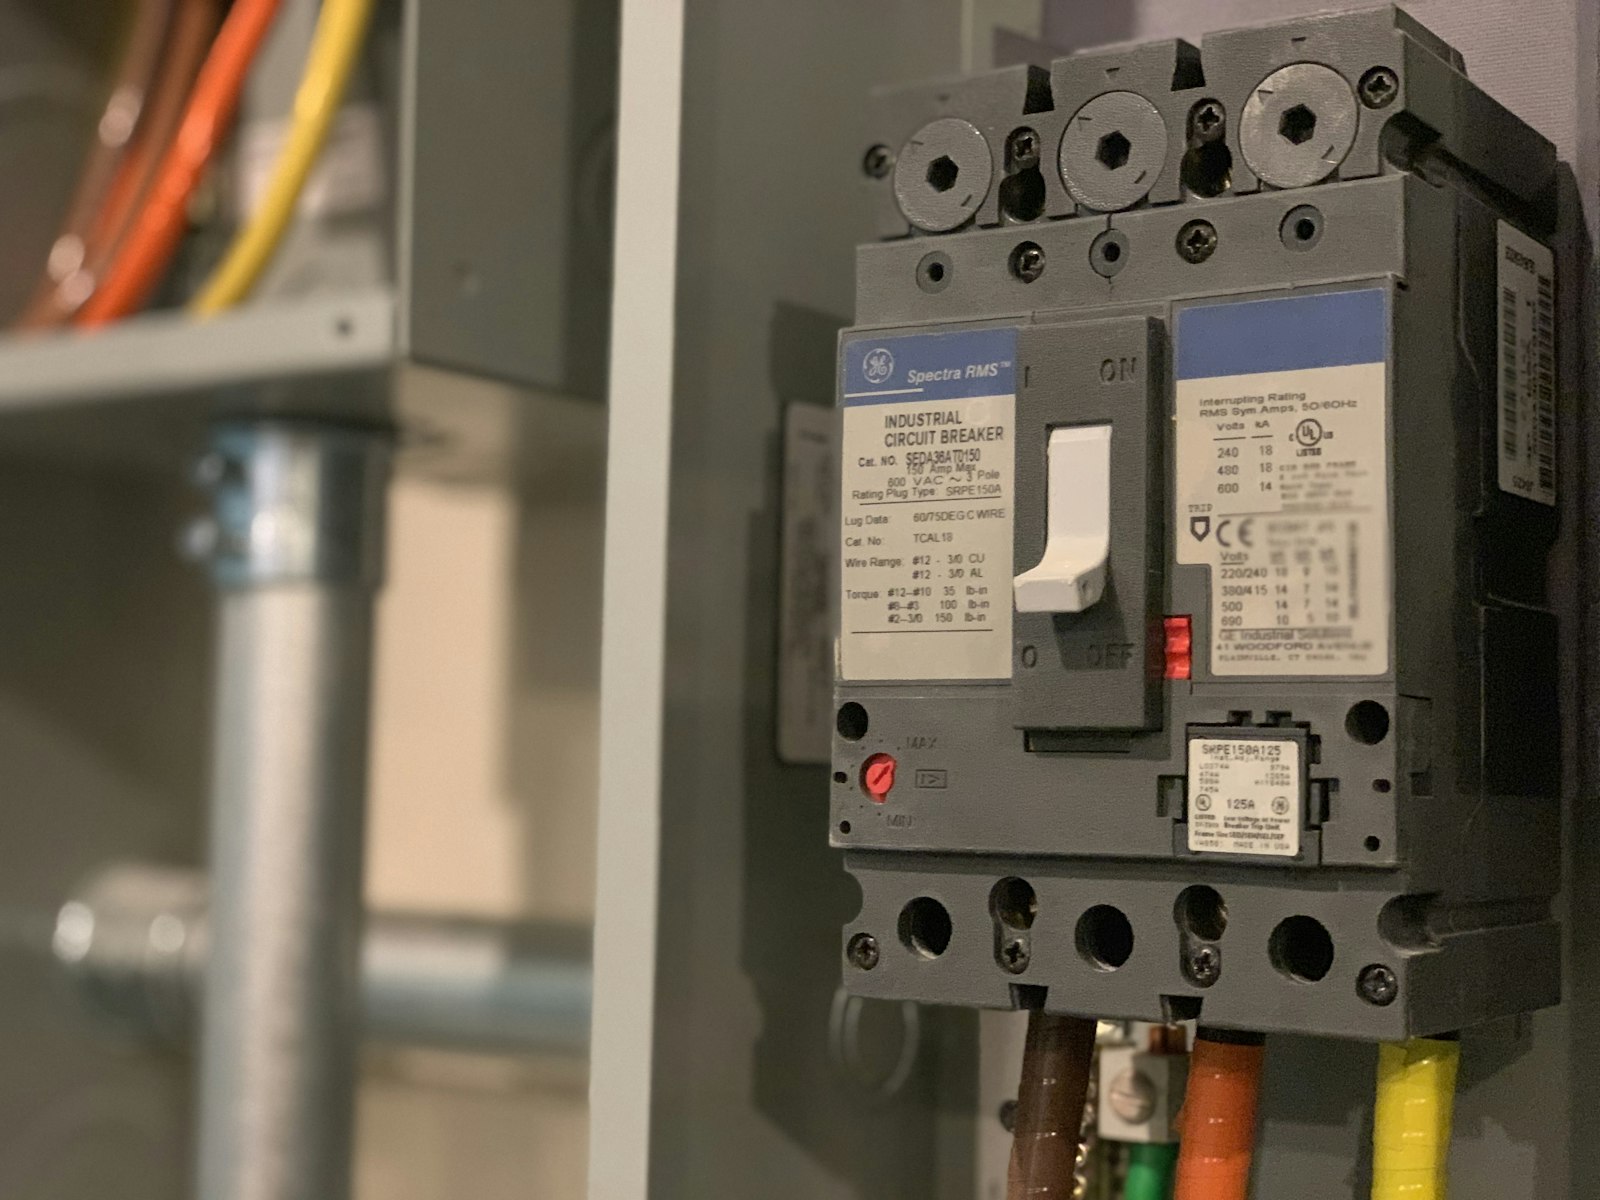
The four systems every insurer asks about
Most insurers ask when your roof, electrical, plumbing and heating were last updated. Homes with updated systems and good records are much easier to place, often with an admitted carrier. See Roof Age and Home Insurance.
Older-home coverage to get right
- Ordinance or law coverage. Rebuilding an older home means meeting today’s codes, which can be expensive. Many policies include only a small amount unless you increase it. See Home Insurance Sub-Limits.
- Replacement cost, not market value. Unique materials and craftsmanship can cost more to rebuild. See Are You Underinsured?
- Earthquake. Older homes on raised foundations can be vulnerable, and a seismic retrofit can earn a discount on earthquake coverage. See Earthquake Insurance in California.
- Wood stoves and fireplaces. Common in older foothill homes. Disclose them and keep them inspected.
Making an older home easier to insure
- Gather records of every update, with dates, permits and receipts.
- Get an electrician’s evaluation if you have knob-and-tube wiring, a fuse box or an older panel.
- Have a plumber check for galvanized or polybutylene pipes.
- Replace an aging water heater and add leak sensors or an automatic water shutoff.
- Address the roof and wildfire basics: Class A roof, ember-resistant vents and a clean Zone Zero.
- Talk to us before major upgrades so you know which ones matter most to carriers.
Buying an older home?
Get your home inspection report to us early. It answers most of the questions insurers will ask, and it helps us find the right carrier before you’re deep into escrow. See Home Insurance Tips for Home Buyers.
See your older home through an underwriter’s eyes
A walk-through looks at an older home’s systems, roof and wildfire exposure the way carriers do, and helps you prioritize the updates that matter most for insurability.
Phil or a member of our team visits your property and looks at it the way insurance underwriters do, so you know where your home stands and what to do next.
- Reviews your home against carriers’ own underwriting guidelines
- Verifies your ISO mapping: the actual distance to the nearest fire station and hydrant
- Identifies and validates mitigation discounts, which are hard to sort out on your own
- Captures the photos and details carriers, and the FAIR Plan if needed, require up front
- Gives you clear next steps to put your home in its best position for coverage
Realtors: listing a home? We can complete a walk-through before you list and send the results to you directly to present to your seller, so insurance answers are ready when a buyer is.
This is an insurability review only. It isn’t a home inspection, an appraisal or a fire agency defensible space inspection.
Book a Walk-Through Email phil@gold.insureLet’s find the right coverage for your home
Own or buying an older home in Gold Country? We’d love to help. Book a 30-minute review with me or request a free quote. Current clients with questions about an existing policy or renewal can reach our service team at team@gold.insure.
Specialists in California’s wildland-urban interface, where homes meet forest, brush and grassland.
Phil Irwin, President, Gold Insurance Solutions. CA License #6000540. General information as of October 2026, not legal advice. Coverage and pricing vary by carrier and home.